

Table of contents:
- Key Summary
- What Is VAT Penalty in the UAE?
- VAT Penalty Rates in UAE
- What Is VAT Late Payment Penalty in UAE?
- What Is a VAT Deregistration Penalty in the UAE?
- What Is Voluntary Disclosure Penalty in UAE?
- How Is VAT Late Payment Penalty Calculated?
- Difference Between Late Filing and Late Payment Penalties
- Other VAT Penalties in UAE You Should Know
- Can VAT Penalty Be Reduced or Waived?
- How to Appeal or Reconsider a VAT Penalty in UAE
- How to Avoid VAT Penalties in UAE
- Common Mistakes That Lead to VAT Penalties
- VAT Penalty – Final Compliance Checklist
- Conclusion
With strict compliance requirements for VAT in the UAE, businesses are eager to learn everything there is to know about the system, its implementation, best practices, and, very importantly, the penalties. The Federal Tax Authority and the Ministry of Finance have clearly stated that non-compliance will incur penalties, thereby encouraging businesses to adhere to the rules.
The government's decisions imposed penalties for various scenarios, including violations concerning the timing of filing and payment, disclosure of omissions, and compulsory deregistration. If your business does not comply with the mandatory rules and deadlines, it will face penalties under Cabinet Decision No. (129) of 2025. This Cabinet decision is declared to replace Cabinet Decision No. (40) of 2017, in order to ease the burden of the compounding penalties system with a less rigid system.
A hugely misunderstood point is that penalties only apply if you don’t report VAT; in reality, you can be fined by the Federal Tax Authority for not paying your VAT on time, for not correcting an error, or even for poor recordkeeping, even though you filed your VAT return accurately and on time. This article is your go-to for understanding VAT penalties in the UAE, common mistakes, and best practices for complying.
What Is VAT Penalty in the UAE?
A VAT penalty in the UAE is a fine imposed by the Federal Tax Authority for compliance violations. These penalties are designed to enhance tax practices and enforce compliance with the VAT regulations. The FTA has clearly outlined violations in the official Administrative Penalties for Violation of Tax documentation. Here are some of them:
- VAT Late return
- VAT Late payment
- Failure to register for VAT as required
- Failure to deregister for VAT after eligibility
- Incorrect VAT calculation or enclosure
- Poor recordkeeping
Each violation is treated differently based on its severity and how long it persisted. In some cases, penalties accumulate over time, resulting in a huge financial burden on businesses. Understanding VAT regulations and compliance practices is crucial for everyone conducting business in the UAE, as even small errors can lead to avoidable large losses.
VAT Penalty Rates in UAE
The late-payment penalty is imposed on unsettled Payable Tax at a rate of 14% per annum for each month or part thereof, starting from the day following the payment due date.
The following table breaks down the VAT violations and their penalties in AED:
Late Payment Penalty | ||||||||
Penalty trigger | Effect | Example | ||||||
VAT not paid on time | 14% annual rate; penalty on the unsettled amount applies within the first month or part thereof | VAT payable = 100,000 1st Month penalty: 100,000 * 14% /12 = 1,166.67 AED | ||||||
Outstanding VAT amount not yet paid | A further monthly penalty based on the 14% annual rate applies for each additional month or part thereof to the unsettled Payable Tax. | 3rd month accumulated VAT penalty: 1,166.67 *3 = 3500 100,000 + 3500 = AED 103,500 | ||||||
Long period delay | Total penalties will hugely increase | For each month or part thereof that the Payable Tax remains unsettled, the monthly penalty is calculated using the 14% annual rate on the unsettled Payable Tax amount. | ||||||
Deregistration Penalty | ||||||||
Registrant does not submit deregistration application on time | AED 1000 monthly for late submission, followed by AED 1,000 on the same date monthly, up to AED 10,000 | The company ceased taxable activity, but applies 3 months late = AED 3000 | ||||||
Late VAT registration Penalty | ||||||||
Eligible person does not submit registration within the timeframe | AED 10,000 | Business misses the deadline and registers late = AED 10,000 | ||||||
Late VAT return filing | ||||||||
Registant does not submit VAT return on time | Start at AED 1000 AED 2000 if repeated within 24 months | VAT return is due on the 28th, but filed on the 30th = 1000 Repeated the next month = 2000 | ||||||
Incorrect VAT return | ||||||||
Registant submits an incorrect tax return | AED 500 (unless corrected within the deadline or by voluntary disclosure with no tax difference) | Sales were entered in the wrong box but corrected after the deadline, with no tax difference = AED 500 | ||||||
Voluntary disclosure of VAT error | ||||||||
Taxpayer submits voluntary disclosure to correct tax return/ assessment or refund application | 1% of the Tax Difference for each month or part thereof, calculated from the day following the due date for the relevant Tax Return or the submission of the relevant tax refund application until the date the Voluntary Disclosure is submitted. | AED 10,000 underdeclared VAT corrected after 3 months = AED 300 | ||||||
Failure to submit VD before audit notice | ||||||||
Error exists but taxpayer does not submit VD before FTA audit notification | 15% on tax difference + 1% per month or part thereof | AED 10,000 tax difference found after 3 months: 1,500 + 300 = AED 1800 | ||||||
Incorrect VAT recordkeeping | ||||||||
Business fails to keep the required tax information | AED 10,000 per violation AED 20,000 if repeated within 24 months | Company can not produce VAT invoices during an FTA review = AED 10,000 | ||||||
Failure to update the tax record | ||||||||
Registrant does not notify FTA of a change requiring tax record amendment | AED 1000 per violation AED 5000 if repeated within 24 months | Trade license address changed, but FTA records are not updated = AED 1000 | ||||||
Arabic records not provided | ||||||||
FTA requests tax data/ documents in Arabic, and the person fails to do so | AED 5000 | FTA asked for Arabic-translated VAT records, and the company does not provide them = AED 5000 | ||||||
Legal representative appointment not notified | ||||||||
Legal representative fails to notify FTA of appointment on time | AED 1000 (Payable by the legal representative personally) | Manager is appointed but not notified to FTA = AED 1000 | ||||||
Legal representative fails to file VAT return | ||||||||
Legal representative does not file the taxable persons’ return on time | AED 1000 first time AED 2000 if repeated within 24 months | Legal representative misses a VAT return deadline = AED 1000 | ||||||
Other VAT penalties | ||||||||||||||||||||||||||
Failure to assist with audit tax | ||||||||||||||||||||||||||
Person/ tax agent/ legal representative does not facilitate tax audit | AED 20,000 | FTA auditor requests access to records and was denied = AED 20,000 | ||||||||||||||||||||||||
Failure to account for VAT on behalf of another person | ||||||||||||||||||||||||||
Registrant is required to calculate tax on behalf of another person, but fails to do so | 14% per annum, monthly or part thereof, applied on unsettled payable tax | Reverse charge VAT of AED 50,000 was not accounted for in one month = AED 583.33 | ||||||||||||||||||||||||
Import VAT not calculated | ||||||||||||||||||||||||||
Person fails to calculate tax due on imported goods | 50% of unpaid/ undeclared tax | AED 20,000 import VAT not declared = AED 10,000 | ||||||||||||||||||||||||
Taxable person fails to display prices inclusive of VAT | AED 5000 | Retail price displayed as AED 100, not including VAT amount = AED 5000 | ||||||||||||||||||||||||
Margin scheme not notified | ||||||||||||||||||||||||||
Taxable person applies tax based on the margin but does not notify FTA | AED 2,500 | Used goods seller applies a margin scheme without notifying the FTA = AED 2,500 | ||||||||||||||||||||||||
Designated Zone goods rules breached | ||||||||||||||||||||||||||
Conditions/procedures for keeping or moving goods in designated zone are not followed | Higher of AED 50,000 50% of tax chargeable on goods | Goods moved between zones without the required procedure, tax exposure: 60,000 = AED 50,000 | ||||||||||||||||||||||||
Tax invoice not issued on time | ||||||||||||||||||||||||||
Person fails to issue tax invoice within legal period | AED 2,500 per case | 4 missed invoices = AED 10,000 | ||||||||||||||||||||||||
Tax credit note not issued on time | ||||||||||||||||||||||||||
Person fails to issue tax credit note within legal period | AED 2,500 per case | 2 credit notes for returned goods not issued = AED 5,000 | ||||||||||||||||||||||||
Person fails to comply with requirements for issuing tax invoices/ credit notes electronically | AED 2,500 per case | 3 cases of non-compliant e-invoice format = AED 7,500 | ||||||||||||||||||||||||
This is why it is advisable to treat VAT as a time-sensitive issue; both filing and payment have time limits that must be respected, or your business will incur additional costs.
Helpful Template: tax invoice format UAE
What Is VAT Late Payment Penalty in UAE?
VAT late payment penalty in the UAE imposes restrictions on reporting and payment practices. Businesses in the UAE are required to pay their VAT by the due date; those who fail to do so are subject to a penalty set by the Federal Tax Authority. The VAT late payment penalty is set at a rate of 14% per annum, for each month or part thereof on the taxable amount only.
It is also important to differentiate between VAT late payment and VAT late filing penalty in UAE, in order to avoid the consequences of each; submitting your VAT reports does not constitute full compliance until you pay the amount by the due date.
Note that if you didn’t file your VAT on time or pay by the due date, multiple penalties will apply simultaneously. That is why, to comply, you need to understand how to avoid late payment penalties and, most importantly, that submitting the return alone is not enough.
What Is a VAT Deregistration Penalty in the UAE?
VAT deregistration in the UAE occurs when a business fails to cancel its VAT registration within 30 business days after it becomes eligible or obligated to do so.
The FTA requires businesses to deregister in the following cases:
- They no longer meet the mandatory threshold (taxable turnovers below AED 375,000 mandatory, AED 187,500 voluntary; each have their own cases for valid deregistration)
- They cease making taxable supplies/ activities
If a business delays the deregistration request, a penalty will be imposed for violating the VAT regulations. The FTA declared that failure to submit a deregistration application within the timeframe specified in the Tax Law will result in an AED 1,000 penalty, and, on the same date each month thereafter, up to AED 10,000.
This is why it is advisable to regularly review your VAT status and take action if the conditions for VAT deregistration are met.
Read also: TRN Verification in UAE
What Is Voluntary Disclosure Penalty in UAE?
A voluntary disclosure penalty is applicable when a business is late in notifying the FTA of an error or omission in a Tax Return, Tax Assessment, or Tax refund, subject to the conditions in the Tax Procedures Law. The FTA allows businesses wishing to fix issues to submit a voluntary disclosure request in certain circumstances, such as follows:
- Underreported VAT liabilities
- Overclaimed input VAT
- Incorrect transactions classifications
- Calculation of payable tax is less than required
It is important to note that where an error results in Payable Tax being understated by AED 10,000 or less, the error may generally be corrected in the VAT Return for the tax period in which the error is discovered, given the applicable conditions are met. If there is no return through which the error can be corrected, a voluntary disclosure may be required. It is also mandatory to request a voluntary disclosure within 20 business days from the date when the Taxable Person became aware of the error to avoid more penalties.
The voluntary disclosure penalty is decided based on:
- The size of the error made
- How long the error has been left uncorrected
- Whether the correction increases the VAT owed
The purpose of this disclosure is to ensure that the ‘Due Tax” matches the “Payable Tax” that should have been calculated.
How Is VAT Late Payment Penalty Calculated?
VAT late payment in the UAE is calculated based on how long the amount was left unsettled after the due date. The penalty system applies immediately after the deadline passes without settlement of the outstanding amount, and the penalty rate is set at 14% applied for each month or part thereof. This is part of the new approach the UAE is imposing: an interest-like monthly accumulation; the penalty starts with an initial charge that accrues. Here is a breakdown of the process to help you understand the full concept:
Most businesses do not fully grasp how fast penalties accumulate. At first glance, it may seem like a small, manageable amount, but over time, it accumulates to a large sum that might affect your business later.
From a technical perspective, VAT liabilities should be closely monitored to ensure funds are available even before the filing deadline. If a business fails to meet the deadline, it is crucial to resolve the outstanding VAT obligation before it accumulates further.
Difference Between Late Filing and Late Payment Penalties
One of the most confusing aspects of VAT penalties is the difference between late payment and late filing penalties. Although they are distinct non-compliance practices, people often mix them up. Here is a clear breakdown of late payment penalties and late filing penalties:
Late payment penalties
VAT late payment penalties apply when the amount owed is not paid by the due date or after filing. Delayed payment results in accumulated penalties over time.
Late Filing penalties
VAT late-filing penalty in the UAE applies when the return is not submitted by the deadline. This results in administrative penalties.
Here is the catch: both late payment and late filing penalties can be applied simultaneously. If a business fails to submit the VAT return on time and also fails to pay by the due date, a separate penalty will be applied for each violation.
It is very important to understand the distinction; many businesses assume that filing on time is enough for compliance, which is not true, and it will cost your business.
To ensure compliance with FTA rules and reduce the risk of penalties, it is advisable to maintain clear, organized VAT records, meet deadlines, and settle all payments before their due dates.
Helpful Template: UAE VAT Return 201 Form
Other VAT Penalties in UAE You Should Know
The Federal Tax Authority has imposed set penalties for different violations. Some of these penalties apply to non-compliant practices such as incorrect recordkeeping, voluntary disclosure, and late deregistration.
Here is an explanation for some VAT violations:
Late VAT registration
This penalty is applicable when a business fails to register within the mandatory timeframe.
Non-filing
Applied when the VAT return is not submitted by the due date.
Incorrect VAT recordkeeping
Penalties apply when businesses fail to keep invoices, VAT documents, and records.
The VAT penalty system is designed to be viewed as an ongoing process rather than a simple filing task.
The Federal Tax Authority declared that VAT returns must be submitted and any Payable Tax must be settled within 28 days from the end of the relevant tax period.
Can VAT Penalty Be Reduced or Waived?
The Federal Tax Authority has enacted an exceptional law to waive VAT violations. This system is designed for businesses that can provide a valid justification, supported by credible documentation, to excuse violations of VAT regulations.
The VAT penalty reconsideration is neither automatic nor accessible; it must be obtained through an official review process conducted by the FTA.
Penalty reconsideration
The FTA accepts review and reconsideration requests in the following cases:
- Exceptional or foreseen circumstances
- Technical issues
- Proven compliance errors
- Genuine mistakes supported by documentation
It is also important to note that filing a reconsideration request does not guarantee acceptance. But rather, the case will be processed and reviewed, and thereafter, the Federal Tax Authority will notify the relevant party of the status of their outstanding case regarding penalty assessment. Supporting your case with documentation of VAT records and transaction history helps strengthen it before the FTA.
How to Appeal or Reconsider a VAT Penalty in UAE
In case your business was subjected to a VAT penalty, you are allowed to submit a request for reconsideration of your case within 40 business days from the date of notification of the FTA’s decision imposing the penalty, via the UAE Emaratax portal.
You will also need to provide supporting evidence and documentation for your argument. Here are the steps to follow when submitting a reconsideration request:
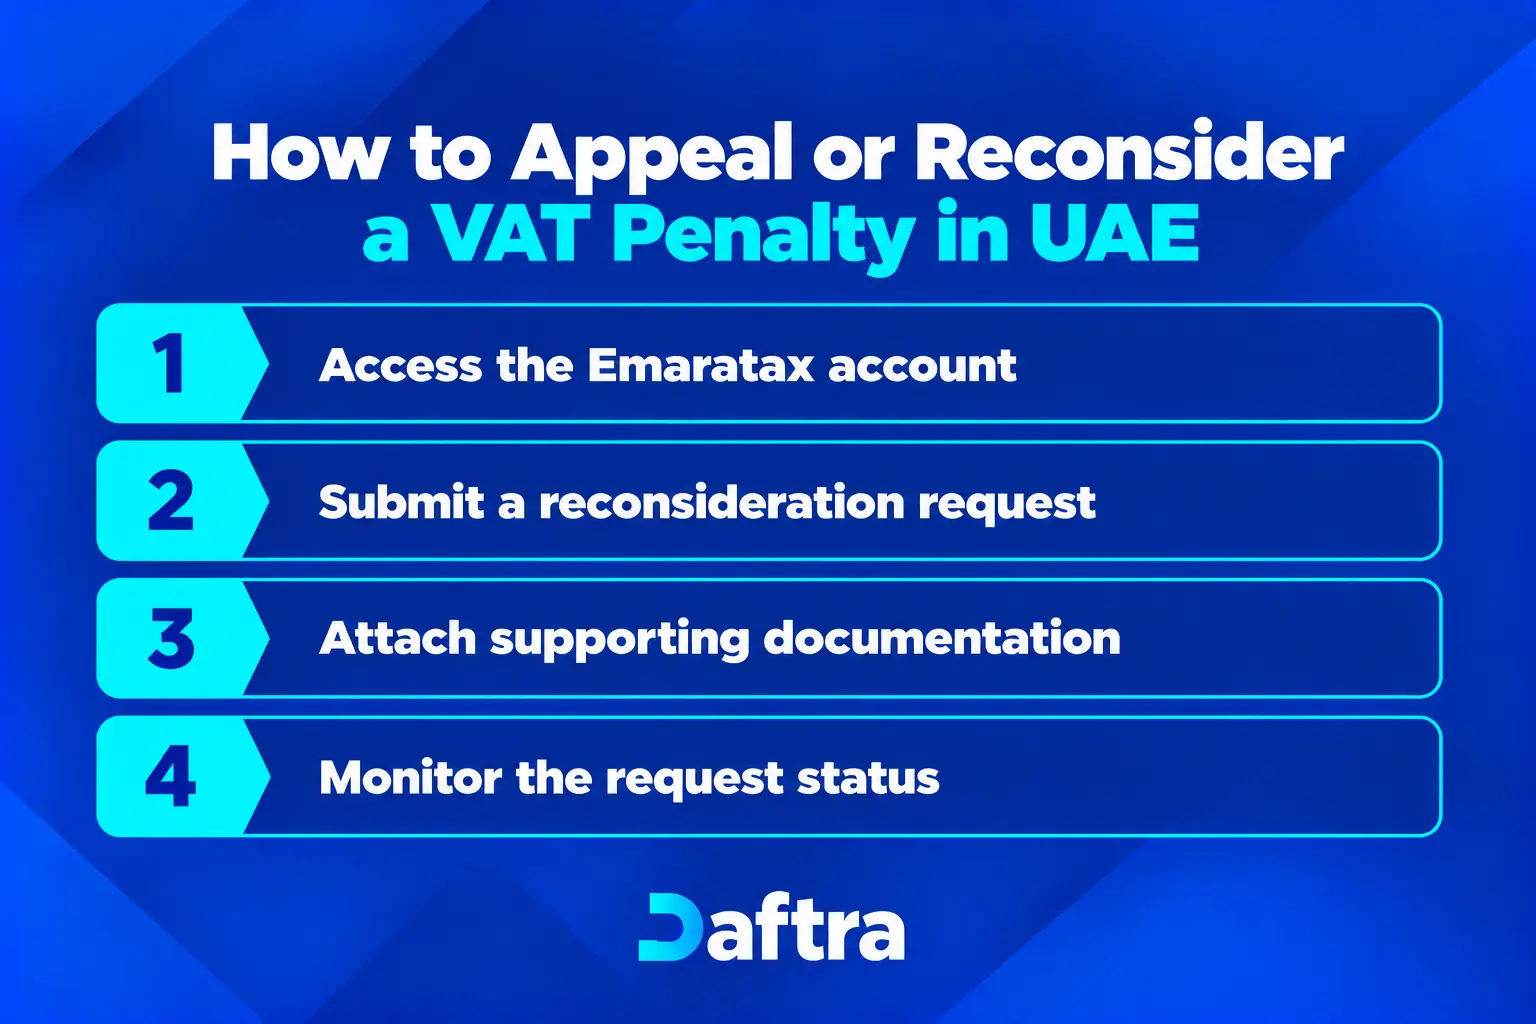
1. Access the Emaratax account
Log in to your Emaratax account to locate the penalty or violation.
2. Submit a reconsideration request
Explain clearly why this penalty should be reviewed.
3. Attach supporting documentation
Make sure to include supporting evidence for your case.
4. Monitor the request status
Track the case updates or requirements closely.
Make sure you submit your reconsideration request within the allowed time frame (40 business days) to ensure the request is accepted and reviewed. The Federal Tax Authority will notify you via the Emaratax portal of any updates or decisions regarding your submission.
How to Avoid VAT Penalties in UAE
Protecting your business from VAT late payment penalties may seem complicated, but it is actually very simple. If you treated VAT as an ongoing responsibility, not just a one-time task, your business will be VAT penalty-free.
Here is how to stay compliant with FTA VAT rules:
Track VAT liabilities regularly
You should calculate what you owe for VAT early on
Set reminders for deadlines
Stay ahead of due dates by setting calendar alerts
File & pay early
Filing your returns and paying early ensures avoiding penalties
Maintain financial records
Keep your records organized for easier VAT calculation
Ensure cash flow
Make sure you have enough funds to cover VAT liabilities on time
Common Mistakes That Lead to VAT Penalties
Avoiding penalties can be achievable when you understand the best practices for VAT compliance.
Here is a table of common mistakes, consequences, and how to prevent them.
| Mistake | Consequences | Prevention |
| Confusing filing with payment | Late payment penalty | Pay the VAT due by the applicable payment deadline |
| Cash flow delays | Missing payment deadlines | Plan cash flow for VAT dues |
| Incorrect VAT classification | Errors requiring correction + possible penalties | Review the VAT treatment for transactions regularly |
| Flawed recordkeeping | Inaccurate reporting + poor compliance | Maintain an organized VAT record |
| Last-minute submission | Risk of missing deadline + possible errors | Prepare the VAT return early before the due date |
Read also: VAT Exemptions in the UAE
VAT Penalty – Final Compliance Checklist
Ensuring you are ready to file returns and make on-time VAT payments is essential to VAT compliance. Here is a checklist of the best VAT- related practices to stay compliant and avoid penalties from the Federal Tax Authority.
To achieve full compliance with the Federal Tax Authority, you must view VAT as a whole process that must be completed within a strict time frame. VAT in UAE requires strict recordkeeping, accurate return filing, timely payment, and consistent monitoring.
Conclusion
VAT in the UAE is meant to be a fully integrated system connecting every angle of compliance-mandatory behaviors to ensure businesses’ understanding and adherence to the law. One of the most confusing points is filing and payments. People often mix up filing the returns with actually paying the VAT, thinking that filing alone is enough.
The Federal Tax Authority has set strict penalties for late filing and late payment, making a clear distinction between them. The penalty for late payment is calculated using an interest-like monthly accrual system, with 14% per annum applied for each month or part thereof on unsettled Payable Tax, beginning from the day following the payment due date. This is much more flexible than the old system, which accumulates charges for each day a payment is late. A common violation in the VAT system is the voluntary disclosure. When a business discovers an error and wishes to fix it, it is required to file a disclosure request within 20 business days from the date the taxable person becomes aware of an error where the error results in understated Payable Tax of more than AED 10,000, subject to the applicable rules.
With the system’s aim to eas VAT penalties, it allows the submission of a reconsideration request regarding an FTA decision within 40-days of notification, subject to applicable requirements. Submitting a reconsideration request does not automatically cancel or waive the penalty. This option is set with strict rules for providing evidence and documentation to prove an unintended compliance error.
The new penalty system is designed to ensure compliance with VAT rules, including filing returns accurately, keeping organized financial records, and paying VAT on time.



 Invoicing
 POS
 Offers
 Installments
 Sales Commission
 KSA E-Invoice Software
 EGY E-Invoice Software
 JO E-Invoice Software
 E-Invoice Software
 Chart of Accounts
 Asset Management
 Cost Centers
 Expenses
 Cheque Cycle
 UAE VAT-Tax
 Product Management
 Purchases
 Purchase Cycle
 Suppliers
 Requisitions
 Stocktaking
 Organizational Structure
 Personnel Management
 Attendance and Leave
 Contracts
 Payroll
 Requests
 Work Orders
 Booking Management
 Rental and Unit Management
 Time Tracking
 Work Flow
 Lease Contracts
 Manufacturing Management
 Client Follow-Up
 Loyalty Points
 Points and Credits
 Memberships
 Insurance Management
 Daftra ERP Full App
 Point of Sales App
 Point of Sales for Desktop – Support Offline Mode
 AI Expenses Scanner App
 Employee Attendance, Sign & ESS App
 E-invoice Reader App
 Inventory Stocktaking App