

What Is Profit and Loss Account and How Is It Prepared?
Table of contents:
- Key Summary
- What Is the Profit and Loss Account?
- What is the P&L formula?
- What Are the Benefits of the Profit and Loss Account?
- Items and Components of the Profit and Loss Account
- Profit and Loss Account Format
- How to Prepare the Profit and Loss Account?
- What Is the Profit and Loss Account Closing Entry?
- What Is the Relationship Between the Profit and Loss Account and the Balance Sheet?
- P&L Account and Income Statement
- Difference Between the Profit and Loss Account and the Trading Account
- What Is the Relationship Between the Profit and Loss Account and the Chart of Accounts?
- What are common P&L account mistakes?
- Limitations of Profit and Loss Account
- How Daftra Helps You Prepare the Profit and Loss Account
- Frequently Asked Questions
- Conclusion
The profit and loss account answers a fundamental question: has your company achieved satisfactory profits, or has it incurred significant losses?
The profit and loss account is a report that tells the story of your business activity step by step through clear, logical numerical data, starting with earned revenues, followed by incurred expenses, and ending with net profit or loss.
Whether you are a business owner, financial manager, or investor, we summarize our accounting expertise to explain the profit and loss account and its role in evaluating an enterprise's success, as one of the most important final accounts.
What Is the Profit and Loss Account?
The profit and loss account is one of the final accounts that shows a company's revenues and expenses. It is prepared annually or quarterly to evaluate the company’s financial performance. If revenues exceed expenses, the result is net profit; if expenses exceed revenues, the result is a net loss.
What is the P&L formula?
The Profit and Loss (P&L) formula calculates a business’s profitability over a specific period by comparing revenue with costs and expenses. It helps businesses determine their gross profit, operating profit, and net profit or loss.
The main P&L formulas are:
- Gross Profit = Net Sales (Revenue) − Cost of Goods Sold (COGS)
- Net Operating Profit = Gross Profit − Operating Expenses
- Net Profit Before Taxes = Net Operating Profit + Other Income − Other Expenses
- Net Profit or Loss = Net Profit Before Taxes − Income Taxes
To calculate net profit, a business starts with sales revenue, subtracts the direct costs of producing or purchasing the goods or services sold, then deducts operating and other expenses, and accounts for additional income and taxes.
These calculations help business owners understand how much they earn after covering their costs, identify expenses that may be reducing profitability, and make informed decisions about pricing, sales, and cost management.
For example, a business generates SAR 20,000 in net sales during a month, with a cost of goods sold of SAR 8,000 and operating expenses of SAR 5,000. It also earns SAR 500 in other income, incurs SAR 300 in other expenses, and pays SAR 1,200 in income taxes.
Using the P&L formulas:
- Gross Profit = 20,000 − 8,000 = SAR 12,000
- Net Operating Profit = 12,000 − 5,000 = SAR 7,000
- Net Profit Before Taxes = 7,000 + 500 − 300 = SAR 7,200
- Net Profit = 7,200 − 1,200 = SAR 6,000
Therefore, the business earns a net profit of SAR 6,000 for the month after accounting for its costs, expenses, other income, and taxes. This example shows how the P&L formula helps business owners understand their profitability and identify opportunities to manage costs and improve financial performance.
What Are the Benefits of the Profit and Loss Account?
The profit and loss account is an essential financial tool that institutions use to assess performance over a specific period.
It is not limited to measuring net profit or loss; it provides a comprehensive view of how resources are managed and revenues are generated, helping support accurate strategic decisions that strengthen the company’s stability and growth.
The objectives of the profit and loss account include:
- Analyzing spending and rationalizing expenses: Identifying activities and sectors where significant amounts of money were spent and those where spending was limited, thereby providing solutions to reduce and optimize costs.
- Identifying expansion opportunities: Determining whether the company can expand its activities and identifying sources of financing and investment.
- Evaluating performance and encouraging future investments: Helping investors assess the financial performance of institutions and companies that may be suitable for future investment.
- Facilitating the preparation of tax returns: Simplifying the process of filing tax returns and paying taxes.
- Distinguishing between revenue and profit: Helping businesses understand the difference between increasing sales revenue and generating higher profits.
This happened with a Saudi distribution company when it noticed sales increased during the year, but net profit did not grow at the same rate. By analyzing its profit and loss statement, the company identified rising costs and increased sales discounts as the reasons for the difference.
This analysis helps businesses identify which operational stages are reducing profitability and where they can control costs to improve financial performance.
In short, the profit and loss account matters because it analyzes spending patterns, identifies expansion opportunities, supports investor decisions, and helps meet tax obligations. Therefore, relying on this account represents a vital step toward accurately understanding financial performance and developing more effective plans.
Items and Components of the Profit and Loss Account
Generally, the profit and loss account in commercial and financial companies does not differ from that of industrial or other profit-oriented institutions. Therefore, all necessary items and components must be included in this account to ensure accurate results.
The profit and loss account can be divided into two main sides: the credit side and the debit side, each of which includes several items as follows:
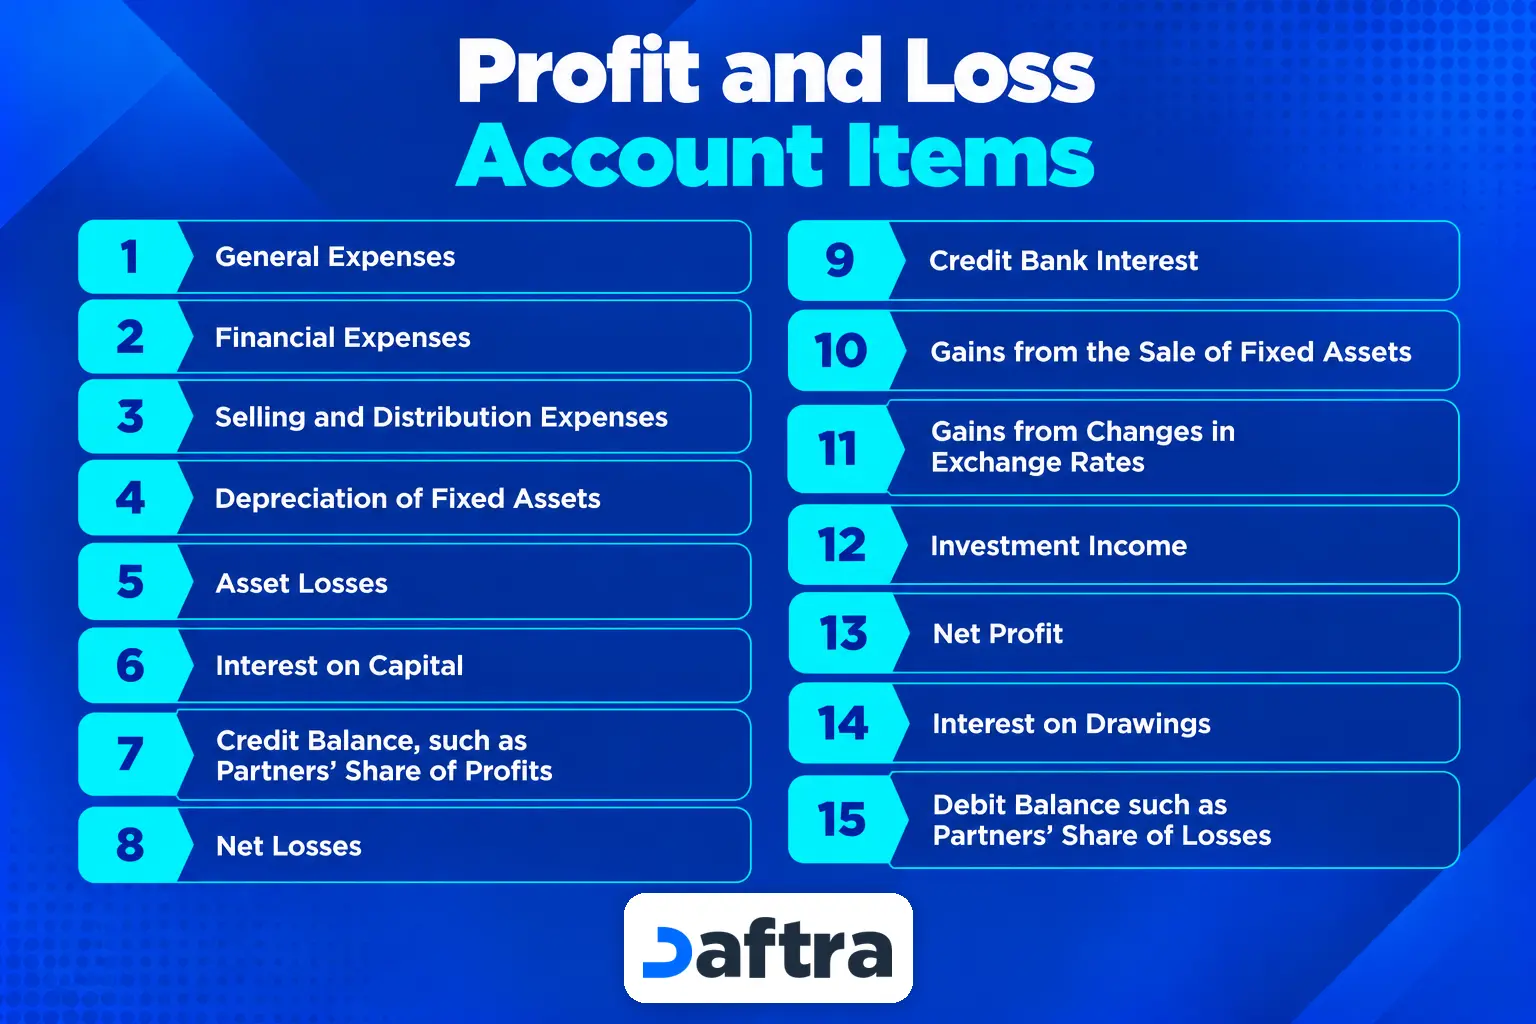
1. General Expenses
General expenses in the profit and loss account include wages and salaries, compensation, travel allowances, taxes and fines, electricity and water bills, and other service charges.
2. Financial Expenses
These include lending and borrowing interest, bank charges, debit interest, losses resulting from exchange rate and currency differences, and all expenses incurred to obtain financing for activities and projects.
3. Selling and Distribution Expenses
These are the costs incurred to sell the products or services the company or institution provides, such as marketing expenses, agents’ commissions, transportation and distribution costs, wages and incentives for sales and marketing staff, and expenses related to renting or purchasing properties, warehouses, and sales outlets.
4. Depreciation of Fixed Assets
Depreciation of fixed assets in the profit and loss account refers to allocating the cost of a fixed asset used in the production process over its useful life.
5. Asset Losses
Losses resulting from asset sales, cash flow or liquidity shortages, financial risks, and damaged goods or production disruptions.
6. Interest on Capital
Interest on capital in the profit and loss account is considered a reward partners receive for their investments in the company. It is debited to the profit and loss account, as it is an expense paid by the company.
7. Credit Balance, such as Partners’ Share of Profits
This item in the profit and loss account refers to the distribution of net profit among partners according to their agreement, after deducting all expenses and interest on capital. Shares may be equal or different, depending on each partner’s contribution.
8. Net Losses
Net losses are an undesirable result in the profit and loss account and indicate that expenses exceed revenues. Therefore, they appear on the debit side of the profit and loss account.
9. Credit Bank Interest
This refers to interest the company earns from banks on deposits or current accounts.
10. Gains from the Sale of Fixed Assets
The profit realized by the company when it sells one of its fixed assets (such as buildings or machinery) at a price higher than its book value.
11. Gains from Changes in Exchange Rates
These are profits realized when the value of a foreign currency held by the company increases against the local currency due to market fluctuations.
12. Investment Income
Investment income is an additional, important source of revenue in the profit and loss account, earned from the company’s investments in shares, bonds, or real estate.
13. Net Profit
Net profit is the final profit a company earns after deducting all expenses, including the cost of goods sold, operating and non-operating expenses, and taxes, from its revenue and accounting for other income.
14. Interest on Drawings
Interest on drawings in the profit and loss account is the interest paid by partners on amounts they withdraw from the company for personal use, which reduces partners’ capital equity.
15. Debit Balance such as Partners’ Share of Losses
This represents the proportion of losses the partners bear during a specific financial period.. It also reduces partners’ capital equity and appears as a debit balance.
In summary, the profit and loss account includes items that illustrate a company’s financial performance during a specific accounting period.
It includes various expenses (general, financial, selling, and depreciation), along with gains and losses from operating and investment activities, interest on capital and drawings, and the partners’ share of profits or losses.
Together, these elements show the institution's true financial performance and help determine net profit or net loss.
Profit and Loss Account Format
To ensure accurate financial analysis and performance evaluation over a specific accounting period, the profit and loss account is prepared in an organized format that clearly shows the relationship between revenues and expenses. Below is the format of the profit and loss account:
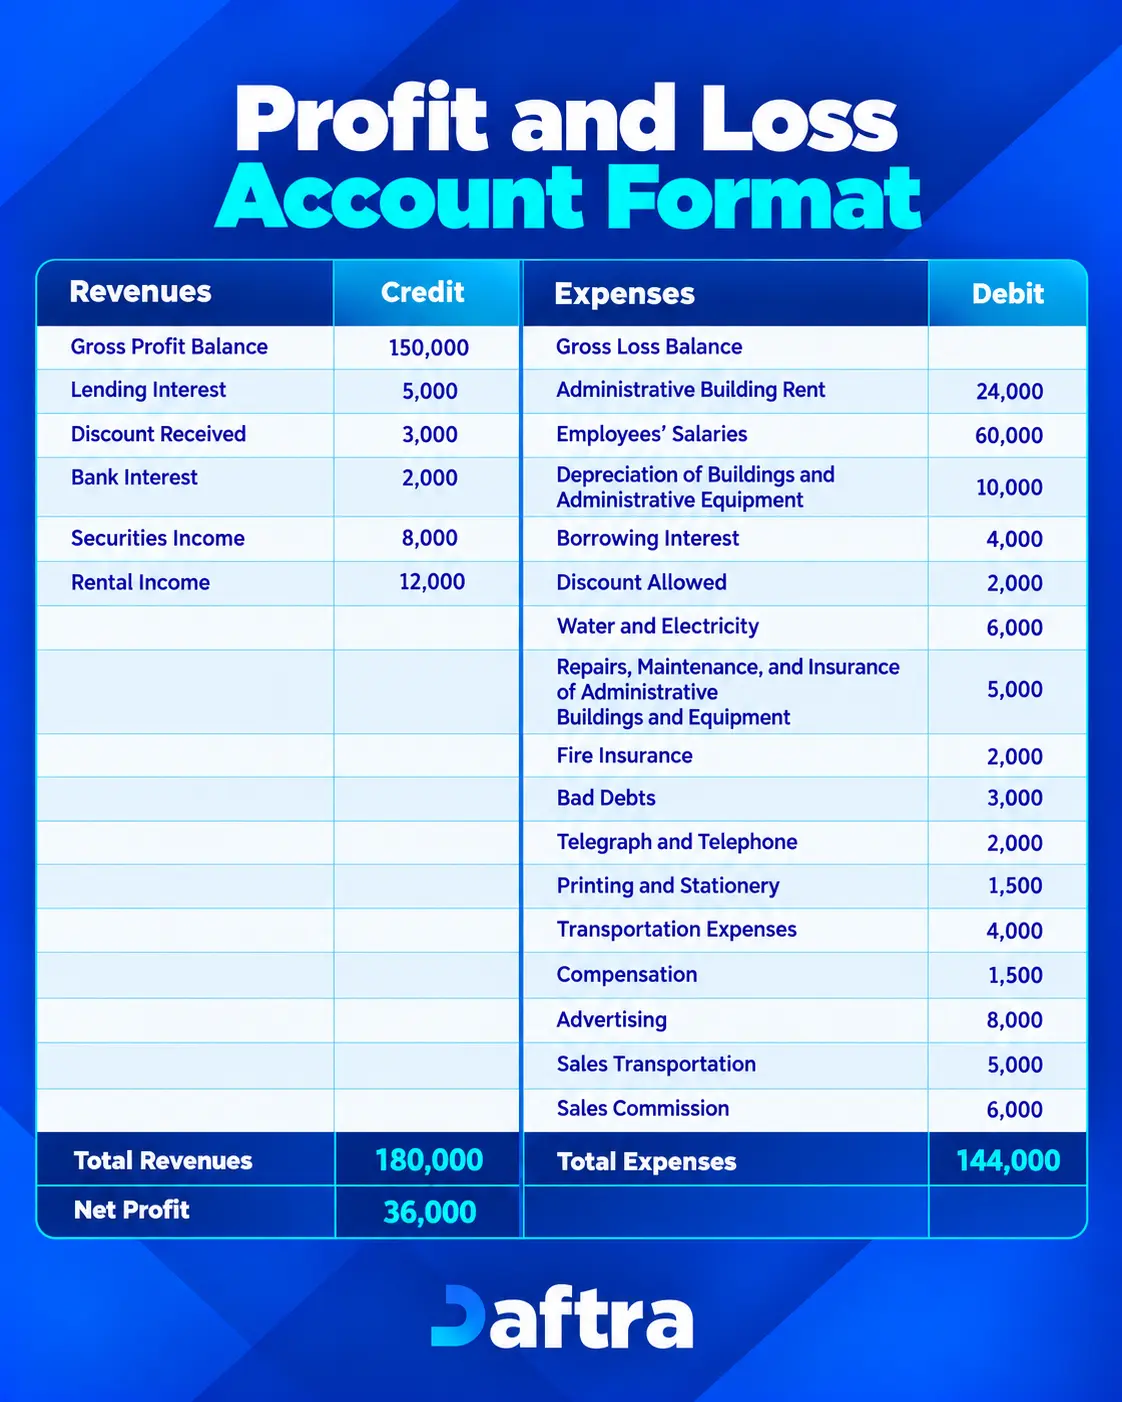
The profit and loss account format consists of a two-sided table: the credit side, which includes revenues and gains, and the debit side, which records all expenses and costs.
By totaling revenues and expenses, the net profit or net loss is calculated, reflecting the institution’s financial performance.
If revenues exceed expenses, the business records a net profit; if expenses exceed revenues, it records a net loss.
How to Prepare the Profit and Loss Account?
The profit and loss account measures a company’s performance and financial condition. This account presents a complete picture of the company’s profits, expenses, and costs related to its activities.
Therefore, it is always recommended to prepare it carefully to avoid fines and interest. The main steps to prepare the profit and loss account are as follows:
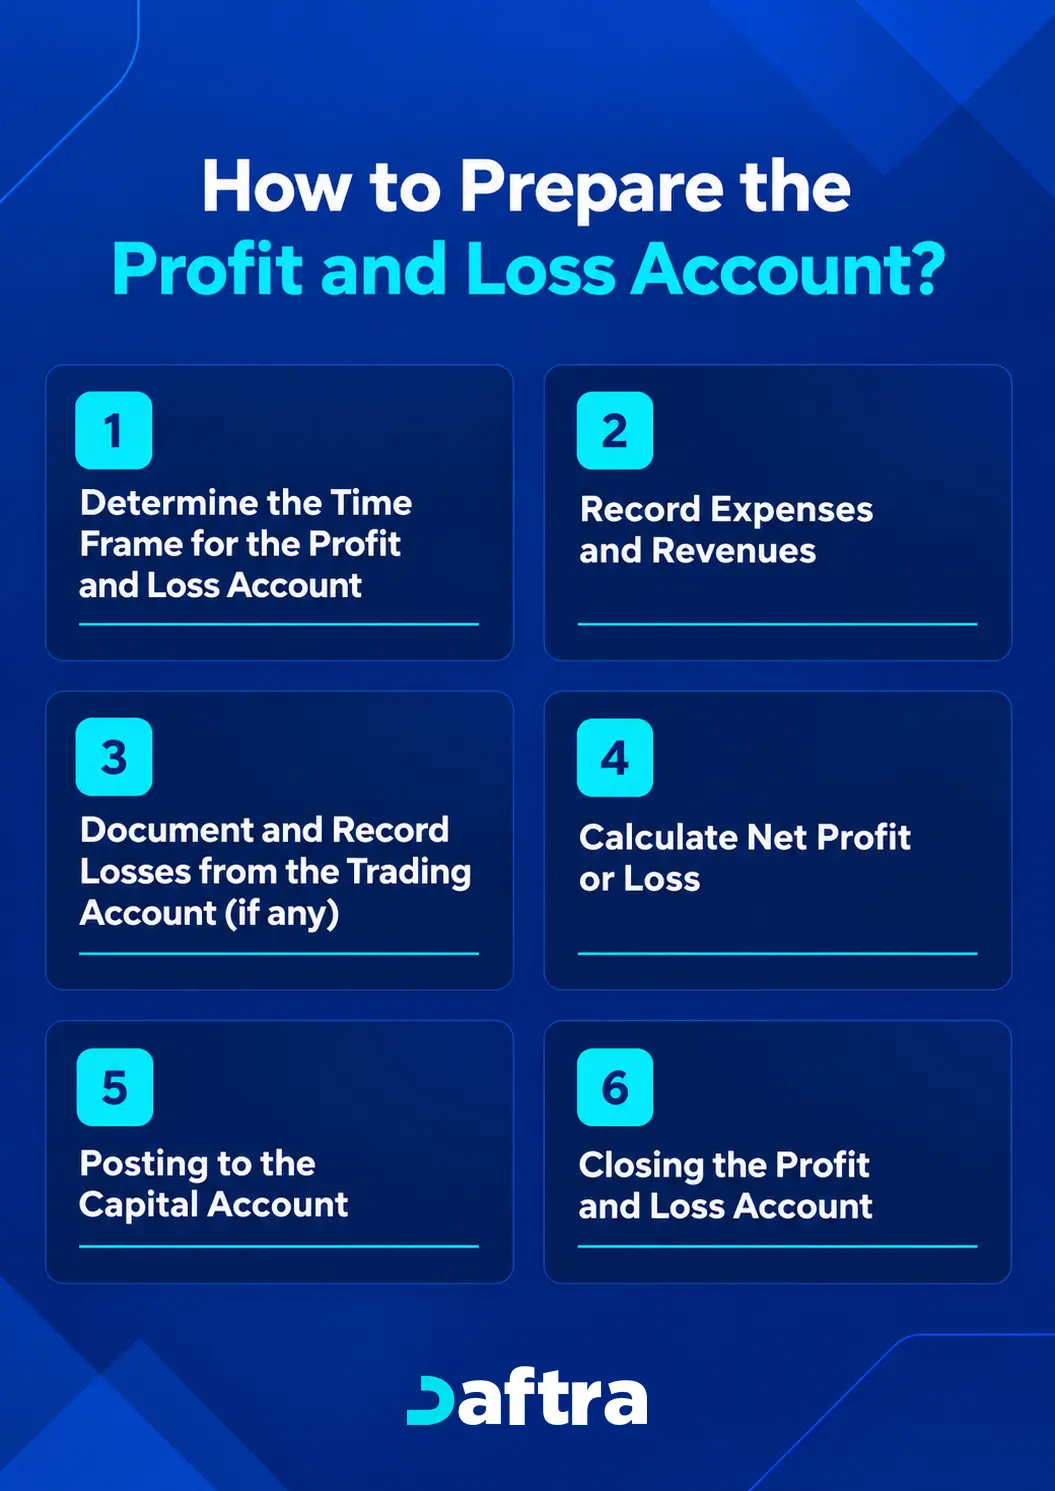
1. Determine the Time Frame for the Profit and Loss Account
First, the period during which net profits or expenses will be determined and calculated must be defined.
2. Record Expenses and Revenues
Record all expenses and revenues from the beginning up to the point of preparing the profit and loss account. Keep records showing the volume of profits and expenses resulting from the company’s activities, and record only revenues generated from the company’s activities in a table.
3. Document and Record Losses from the Trading Account (if any)
Losses arising from the trading account, if any, should be recorded. Enter expenses such as commissions, advertising costs, and other previously mentioned expenses on the debit side, and record revenues on the credit side.
4. Calculate Net Profit or Loss
Subtract expenses from revenues to get the final result, whether net profit or net loss.
Net Profit (or Loss) = Total Revenues − Total Expenses
To calculate profit or loss, use the following steps:
Use our free discount calculator to easily apply any percentage discount to a number or find the discounted value.
5. Posting to the Capital Account
Post the results, transferring the calculation outcome, whether net profit or net loss, to the capital account. If total credits exceed total debits, the result is net profit. If total debits exceed total credits, the result is a net loss.
6. Closing the Profit and Loss Account
The income statement account is zeroed or closed at the end of the financial year, which will be explained later. The results are then transferred to retained earnings, the profits the company keeps for reinvestment.
It is clear that preparing the profit and loss account involves defining the time period, accurately recording all expenses and revenues, documenting losses from the trading account if they exist, calculating net profit or loss by comparing total revenues with expenses, transferring the results to the capital account, and finally closing the account at the end of the financial period.
Applying these steps correctly ensures accurate results and supports informed financial decisions that improve the company’s overall performance.
What Is the Profit and Loss Account Closing Entry?
It is the entry that companies prepare at the end of each financial year or accounting period when preparing financial reports and statements. In this step, companies may close certain accounts so that the balances of some accounts become zero at the beginning of the new financial year.
These accounts are placed in the income summary account, which includes one account for profit and another for loss. Then, close credit accounts such as revenues and profits by transferring them to debit accounts, while closing debit accounts such as expenses and costs by transferring them to credit accounts.
What Is the Relationship Between the Profit and Loss Account and the Balance Sheet?
The profit and loss account and the balance sheet are two essential financial statements that provide complementary information about a company's financial performance and position. The profit and loss account shows the company's revenues, expenses, and net profit or loss over a specific accounting period, while the balance sheet presents its assets, liabilities, and equity at a specific point in time.
The relationship between these two statements lies in how the net profit or loss affects the company's equity. For a sole proprietorship, net profit increases the owner's capital, while a net loss reduces it. In a partnership, partners allocate profits or losses according to the applicable arrangements.
Together, these statements help business owners and investors understand both the company's profitability and its financial position. The profit and loss account explains the results of business activities during a period, while the balance sheet shows the financial resources the company holds and its obligations at the end of that period.
A business began the accounting period with equity of SAR 400,000 and recorded the following results during the year:
P&L Account and Income Statement
The profit and loss account and the income statement generally refer to the same financial statement, which shows a company's financial performance over a specific accounting period. Both reports summarize revenue, expenses, and the resulting net profit or loss, helping business owners, investors, and other stakeholders evaluate the company's profitability.
The main difference is terminology rather than purpose. Some countries and traditional accounting contexts commonly use the term profit and loss account, while the income statement is widely used in modern financial reporting.
Both statements typically present the following information:
- Revenue: Income generated from the company's operating and other activities.
- Cost of Sales: The direct costs associated with the goods sold or services provided.
- Operating Expenses: Costs such as salaries, rent, and marketing expenses.
- Other Income and Expenses: Additional income and expenses that affect the financial result.
- Net Profit or Loss: The final result after deducting applicable expenses from revenue.
In practice, both terms describe a report used to assess financial performance, identify revenue and expense sources, and support business decisions. The exact presentation and classification of financial information depend on the applicable accounting standards and reporting requirements.
Difference Between the Profit and Loss Account and the Trading Account
Final accounts, or result accounts that determine the outcome of a company or institution’s activities, are divided into two accounts: Profit and Loss Account and Trading Account.
| Comparison | Trading Account | Profit and Loss Account |
| Purpose | Measures the results of sales and purchasing operations to determine gross profit or loss. | Determines the net profit or loss after accounting for other revenues and expenses. |
| Main focus | Net sales and the cost of goods sold. | Operating expenses, other revenues, and other expenses. |
| Result | Gross profit or gross loss. | Net profit or net loss. |
| Relationship | The result is transferred to the profit and loss account. | Incorporates the result of the trading account to calculate the final net result. |
| Next step | The gross profit or loss is carried forward to the profit and loss account. | The net profit or loss is transferred to the capital account and reflected in the balance sheet. |
What Is the Relationship Between the Profit and Loss Account and the Chart of Accounts?
The chart of accounts is an index of all accounting transactions a company carries out, whether commercial, industrial, or economic. It also contains all the account numbers and names that make up the accounting system.
The accounts in the chart of accounts are divided into two sections:
- Balance Sheet Accounts: These include asset, liability, and equity accounts, which reflect the company’s financial position.
- Profit, Expense, and Revenue Accounts: These represent the outcome of the company’s activities over a specific financial period.
The chart of accounts includes multiple levels, starting with main accounts, followed by sub-accounts, and then more specialized accounts.
Each account group is coded with sequential numbers to track the company's financial and accounting transactions during each financial period.
Thus, the profit and loss account connects to the chart of accounts because it relies on the chart's sub-accounts to accurately measure financial performance over a specific period.
What are common P&L account mistakes?
Errors can distort a company's reported profit or loss, making it harder to evaluate financial performance and make informed business decisions.
The following are some of the most common P&L mistakes and how businesses can avoid them:
1. Recording Revenue in the Wrong Period
Recognizing revenue too early or too late can make a company's financial performance appear stronger or weaker than it actually is. For example, recording revenue before delivering a product or completing a service may overstate income for the reporting period.
2. Misclassifying Expenses
Recording expenses under the wrong categories can distort financial reports and make it difficult to understand where a business spends its money. For example, combining direct costs with operating expenses can make it harder to calculate gross profit and evaluate profit margins accurately.
3. Making Manual Data Entry Errors
Manual accounting entries can contain duplicated transactions, incorrect amounts, misplaced decimal points, or missing figures. Even small errors can affect revenue, expenses, and the resulting net profit or loss.
4. Omitting Transactions or Recording Them Late
Missing invoices, unrecorded expenses, and delayed transactions can give a P&L account an incomplete picture of financial performance. These errors often occur during month-end or year-end reporting when transactions are recorded in the wrong period or overlooked entirely.
5. Failing to Reconcile Financial Records
Failing to reconcile bank statements and accounting records can leave errors, missing transactions, or unexplained differences undetected. Similarly, discrepancies in customer and supplier balances can affect the accuracy of financial reporting.
6. Incorrectly Calculating the Cost of Goods Sold
Incorrect COGS calculations can distort gross profit and profit margins. Businesses may overlook direct labor, materials, purchases, or inventory changes, resulting in an inaccurate assessment of product profitability.
7. Overlooking Depreciation and Amortization
Failing to record depreciation on tangible assets or amortization on applicable intangible assets can overstate expenses or profits, depending on the circumstances and accounting treatment. These non-cash expenses should be recognized in accordance with the applicable accounting standards.
8. Reviewing Financial Reports Infrequently
Reviewing the P&L only at tax filing time can keep business owners from catching reporting errors, rising expenses, and declining profit margins early enough to respond.
Accurate P&L reporting depends on consistent revenue recognition, proper expense classification, complete transaction records, accurate cost calculations, and regular reconciliation. Regularly reviewing financial reports and using reliable accounting processes helps businesses identify errors early and better understand their financial performance.
Limitations of Profit and Loss Account
Although the profit and loss account provides insights into profitability, it cannot show the company’s full financial position or cash availability. Therefore, review it alongside the balance sheet and cash flow statement. Here are some of the main limitations of the profit and loss account:
- Does not show the company’s full financial position: It focuses on revenues and expenses over a specific period but does not provide a complete picture of the company’s assets, liabilities, and equity.
- Does not reflect cash flow directly: A company may report net profit without enough cash available, because revenues and expenses are recorded under accounting rules rather than only when cash is received or paid.
- Does not explain all reasons behind financial results: Although it shows whether a company made a profit or loss, further analysis may be needed to identify the underlying causes, such as rising costs or increased sales discounts.
- Does not guarantee future profitability: The statement reports financial performance for a past period and cannot, on its own, predict future results or guarantee continued growth.
During our work, we came across a company whose profit and loss account showed that it had achieved a net profit over a specific period. However, the company struggled to meet its short-term financial obligations because a significant amount of cash was tied up in inventory.
This highlighted that profit does not necessarily mean sufficient cash or a strong financial position, emphasizing the importance of reviewing the balance sheet and cash flow statement alongside the profit and loss account.
How Daftra Helps You Prepare the Profit and Loss Account
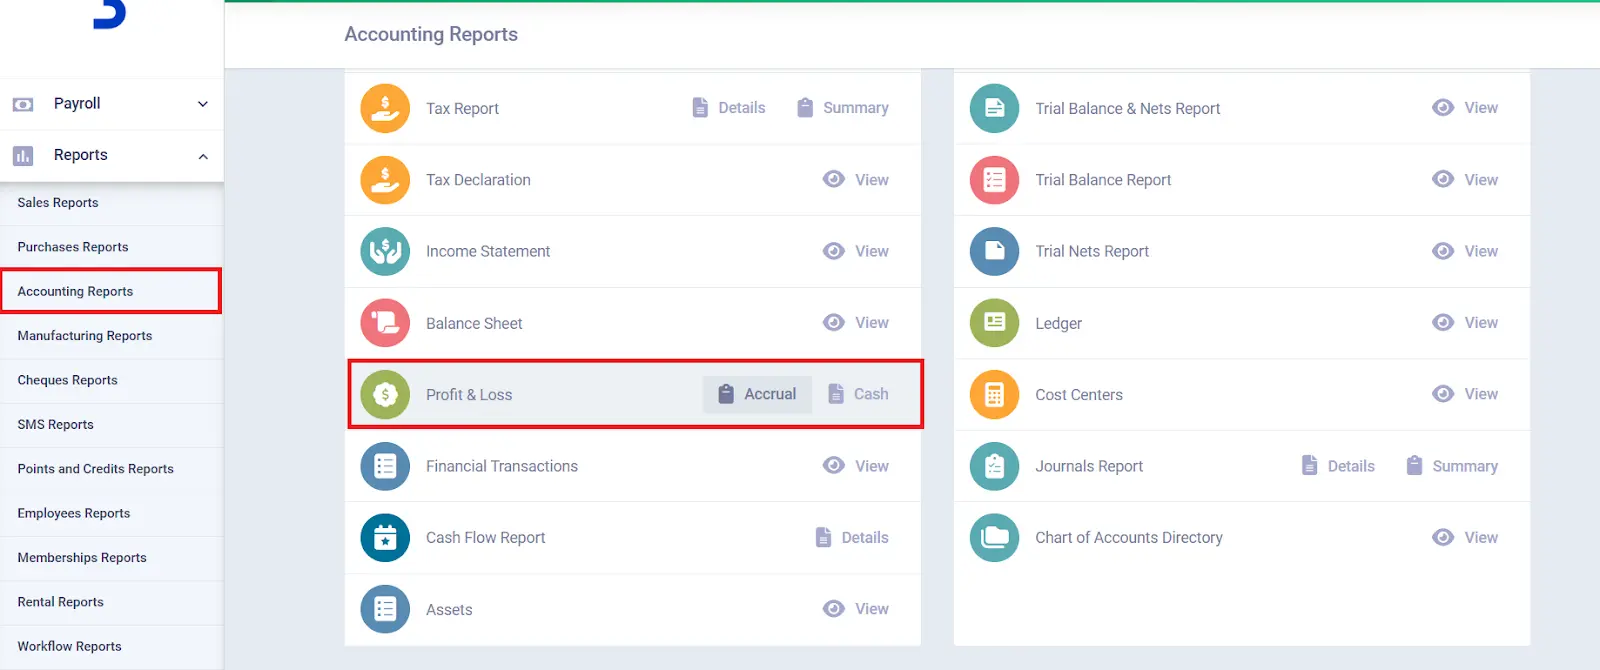
Throughout your accounting operations, final accounts, such as the profit and loss account, are the result. Daftra accounting software makes it easy to run these final account calculations based on the financial transactions you record in the system.
In the end, you can generate these accounts as reports that provide specific financial information based on the type of final account.
Try Daftra now for free for a limited period to explore the system’s capabilities, with detailed guides in multiple formats to simplify your journey using Daftra to manage your business.
Frequently Asked Questions
What are the characteristics of the Profit and Loss Account?
The characteristics of the profit and loss account include:
- The profit and loss account presents the financial performance for a specific period, unlike the balance sheet, which shows the company’s financial position at a particular moment.
- The profit and loss account follows the matching principle and accrual basis, matching revenues with related expenses in the same accounting period, regardless of when cash is received or paid. This allows you to calculate net profit or loss and provides a more accurate picture of the company’s profitability and financial health.
- Transparency and reliability are key characteristics, as it is prepared in accordance with Generally Accepted Accounting Principles (GAAP) or International Financial Reporting Standards (IFRS).
What are the factors affecting the Profit and Loss Account?
The factors affecting the profit and loss account can be summarized as follows:
- Sales volume: Higher sales increase revenues and profit, and vice versa. Competition, marketing efforts, supply and demand, customer preferences, economic recession or growth, exchange rate changes, and inflation influence sales.
- Product pricing strategies: Prices should balance competitiveness, cost coverage, and an acceptable profit margin.
- Discounts and promotions: While they may increase sales volume, they reduce revenue per unit sold.
- Cost of goods sold: Affected by raw material costs, direct labor wages and salaries, other manufacturing costs, shipping, packaging, transportation, distribution costs, and ending inventory value.
- Interest income from investments or deposits, and interest expenses on loans.
- Profits or losses from the sale of fixed assets.
- Income tax, value-added tax (VAT) (only the non-recoverable portion), or property taxes.
Does the Profit and Loss Account appear in the trial balance?
No, the profit and loss account does not appear in the trial balance. Although it is a final account that affects the balance sheet, it is a temporary account that shows changes in the balance sheet during the financial period.
Therefore, it does not appear in the trial balance.
What are the objectives of the Profit and Loss Account?
The profit and loss account aims to:
- Analyze spending and rationalize expenses.
- Identify expansion opportunities for activities.
- Evaluate performance to encourage future investments.
- Facilitate tax filing and payment of due taxes.
The main objective of the profit and loss account is to calculate a project's net profit or loss for a specific period.
How do you summarize the Profit and Loss Statement?
The profit and loss account summary is one of the final accounts used to determine a company’s financial result for a specific period, whether annual or quarterly, by comparing revenues with expenses. If revenues exceed expenses, the company makes a net profit; if expenses exceed revenues, it incurs a net loss.
Which accounts are closed in the Profit and Loss Account?
The accounts closed in the profit and loss account are operational accounts, including:
- Revenues and profits (closed on the credit side).
- Expenses and losses (closed on the debit side).
These accounts are transferred to the profit and loss account to determine net profit or loss.
What are the accounting entries for the Profit and Loss Account?
The accounting entries for the profit and loss account record all revenues and expenses at the end of the financial period, debiting expenses and crediting revenues to arrive at the net result. If revenues exceed expenses, the result is net profit; if expenses exceed revenues, the result is net loss.
Is the Profit and Loss Account debit or credit?
The profit and loss account is a composite account containing both sides: debit for expenses and losses, and credit for revenues and profits. Therefore, it is neither inherently debit nor credit; it depends on the final result, profit or loss.
How is the Profit and Loss Account closed?
The profit and loss account is closed at the end of the financial year by transferring the final result (net profit or loss) to the capital account or retained earnings. This transfer zeroes the account in preparation for a new financial period.
What are the correction entries that affect the Profit and Loss Account?
Correction entries that affect the profit and loss account adjust errors or make adjustments related to expenses or revenues. They directly impact the account’s result, either increasing or decreasing the previously calculated net profit or loss.
Conclusion
The profit and loss account is a key component of financial statements for any institution, alongside the balance sheet and cash flow statement. It provides a true picture of the company’s financial position and the results of its activities by offering ratios and figures on revenues, profits, and expenses.
This helps evaluate how the company manages projects and activities and how much it spends on them. Therefore, accuracy and care are essential when preparing it.



 Invoicing
 POS
 Offers
 Installments
 Sales Commission
 KSA E-Invoice Software
 EGY E-Invoice Software
 JO E-Invoice Software
 E-Invoice Software
 Chart of Accounts
 Asset Management
 Cost Centers
 Expenses
 Cheque Cycle
 UAE VAT-Tax
 Product Management
 Purchases
 Purchase Cycle
 Suppliers
 Requisitions
 Stocktaking
 Organizational Structure
 Personnel Management
 Attendance and Leave
 Contracts
 Payroll
 Requests
 Work Orders
 Booking Management
 Rental and Unit Management
 Time Tracking
 Work Flow
 Lease Contracts
 Manufacturing Management
 Client Follow-Up
 Loyalty Points
 Points and Credits
 Memberships
 Insurance Management
 Daftra ERP Full App
 Point of Sales App
 Point of Sales for Desktop – Support Offline Mode
 AI Expenses Scanner App
 Employee Attendance, Sign & ESS App
 E-invoice Reader App
 Inventory Stocktaking App