

Table of contents:
- Key Summary
- What are Tax Journal Entries?
- Components of Tax Journal Entries
- Importance of Recording Tax Entries
- Tax Journal Entries Example
- Corporate Income Tax Journal Entries
- Sales Tax Journal Entries
- Value Added Tax (VAT) Journal Entries
- How Does Daftra Help You Generate Tax Journal Entries?
- Frequently Asked Questions
- Conclusion
Have you ever wondered how accountants organize and analyze financial data to accurately estimate taxes? Would you like to learn more about the processes and challenges that accountants face in tax processing?
Tax journal entries are among the most important operations in accounting, as they play a crucial role in complying with tax laws and achieving financial transparency. The International Federation of Accountants (IFAC) estimates that companies spend up to 24% of their time processing taxes. As information technology evolves and tax laws change, understanding tax accounting processes becomes increasingly important for both companies and individuals. In this article, we will explore tax journal entry processes in greater detail with practical examples.
What are Tax Journal Entries?
Tax journal entries are accounting records that document and record tax-related transactions and obligations arising from an entity's operations, such as sales, purchases, and tax payments. By recording tax amounts in the appropriate accounts, these entries ensure accurate determination of taxes payable or recoverable, allowing correct presentation in financial statements and reports.
In the context of Value Added Tax (VAT) in Saudi Arabia, these entries involve separating the tax amount from the sale or purchase value. Consequently, output tax is recorded on sales, and input tax is recorded on eligible purchases; subsequent adjusting and payment entries are then made based on the outstanding balance.
Components of Tax Journal Entries
Tax journal entries consist of the following elements:
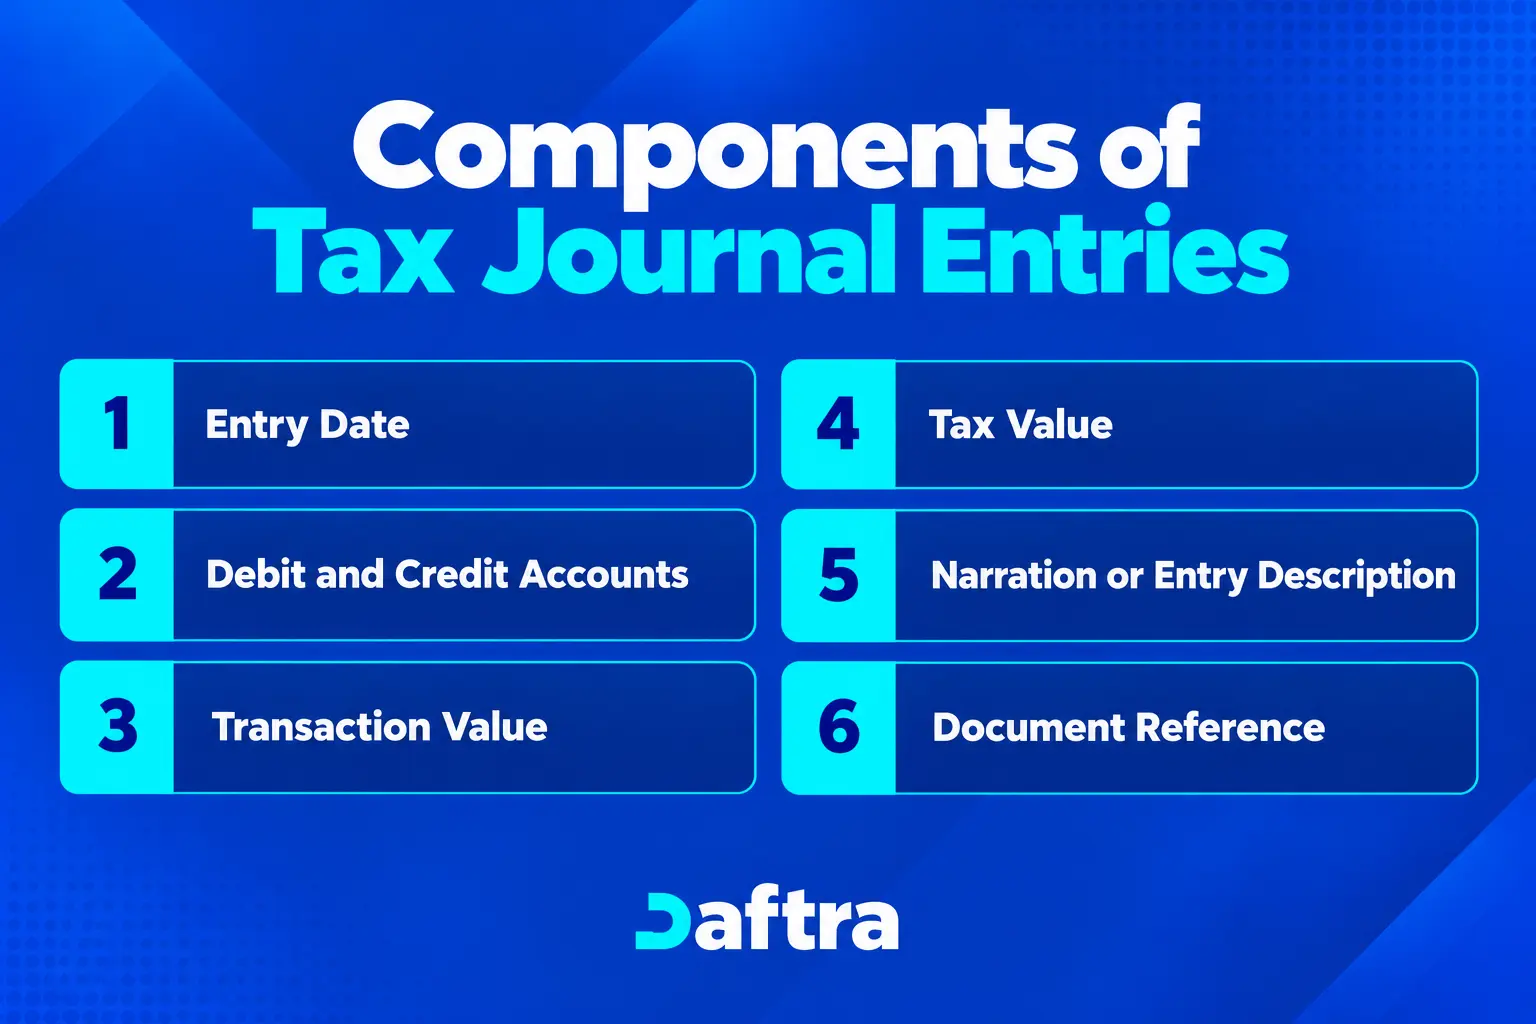
- Entry Date: The date the transaction occurred or the tax liability arose.
- Debit and Credit Accounts: The accounts affected by the transaction, identifying the debit and credit parties.
- Transaction Value: The amount associated with the operation prior to tax calculation, depending on the nature of the transaction.
- Tax Value: The tax amount resulting from the transaction, whether payable, deductible, or recoverable depending on the tax type.
- Narration or Entry Description: A brief description explaining the nature of the transaction and the reason for recording the entry.
- Document Reference: The invoice number, receipt, or supporting document for the entry.
Importance of Recording Tax Entries
The importance of recording tax entries lies in several key areas:
- Accurately determining tax liabilities: By correctly recording transactions and their associated taxes and revenues.
- Facilitating tax reporting: Tax returns require disclosure of transactions related to taxable sales and purchases.
- Ensuring accurate accounting records and reports: By correctly reflecting transactions and their associated tax implications.
- Facilitating tax audits and reviews: By providing accounting records and documentation that can be referenced at any time.
- Assisting in error detection and correction: By identifying and correcting errors before they affect the tax return or liability.
- Enhancing compliance: By minimizing the risk of errors that could lead to fines or penalties resulting from incorrect filings or failure to maintain required records and documentation, which reduces tax-related financial risks.
Tax Journal Entries Example
Based on the Daftra team's experience with a client company, management needed to record a sales transaction correctly by separating the tax amount from the sales value and showing the total amount due from the customer. The company issued a sales invoice for 10,000 SAR, with a tax amount of 1,500 SAR, for a total invoice value of 11,500 SAR.
Consequently, when recording the transaction in the general journal, the sales value was recognized in the Sales account, the tax amount was recorded in the Tax Payable account, and the total invoice value was recognized in the Accounts Receivable account, as follows:
Thus, the entry records the sales value and tax separately while recording the total amount due from the customer, helping organize the transaction's accounting treatment and clearly reflect the tax liability.
Corporate Income Tax Journal Entries
Corporate income tax accounting involves determining the tax due for the period and any advance payments, settling tax liabilities, and recording actual payments or the recovery of overpayments. Accounting treatment may also encompass deferred tax arising from temporary differences, in accordance with the requirements of the accounting standard for income taxes.
The current tax amount is determined based on taxable income and applicable tax legislation; it is not simply calculated by applying the tax rate to net accounting profit. Accordingly, the Saudi income tax system specifies which entities are subject to income tax, including shares of non-Saudi partners in resident capital companies, as well as certain cases involving non-residents who conduct business activities in the Kingdom or derive income from a source within it.
- Income Tax Expense: This account is used to record the income tax expense related to the accounting period. In accordance with IAS 12, income tax expense comprises both current tax and deferred tax.
- Income Tax Payable: This represents the liability for current tax due for the period that remains unpaid as of the financial statement preparation date.
- Income Tax Prepayments: These represent amounts paid by the company in advance against the tax liability. They are subsequently settled against the tax due or may become refundable if they exceed the actual tax liability.
Key types of journal entries for corporate income tax include the following:
Income Tax Recognition Entry
This entry is used to record the current tax expense and the corresponding liability after determining the tax due for the period.
Example
If the income tax due from the company for the period amounts to 50,000 SAR
Income Tax Payment Entry
This records the payment of the tax due to the tax authority. The Zakat, Tax and Customs Authority (ZATCA) provides a service to pay corporate income tax after you submit or amend your tax return.
Example
A company paid the due income tax of 50,000 SAR from its bank account.
Income tax Advance prepayment Entry
Recorded when the company makes an advance payment against its income tax liability.
Example
If a company pays an amount of 20,000 SAR in advance towards income tax
Income Tax Settlement Entry
Recorded when the final tax liability is determined, using the prepayments to reduce the outstanding obligation.
Example
If the final income tax due is 50,000 SAR and the company has made an advance payment of 20,000 Riyals, the advance payment offsets the tax liability.
Journal entry for income tax refund received
Recorded when the company is entitled to a refund—having paid more tax than actually owed—and subsequently receives the amount in its bank account.
Example
If the company has a refundable tax credit of 10,000 SAR and the amount has been received in its bank account.
Deferred Tax Liability Recognition Entry
Deferred tax arises from temporary differences between the carrying amount of an asset or liability and its tax base; this can result in either a deferred tax asset or a deferred tax liability.
Example
If temporary differences between the accounting and tax treatments result in a deferred tax liability of 15,000 SAR
Related reads you might find useful:
What Is The Income Statement and How to Prepare
Sales Tax Journal Entries
Accounting entries for sales tax payable record tax collected from customers as an obligation owed to the tax authority; the entity records the subsequent payment of the due amount after making the necessary tax adjustments. These entries aim to separate the tax amount from the entity's revenue and accurately reflect tax liabilities in the accounting records.
They can be classified as follows:
Sales Tax Recognition Journal Entry
This entry is used to record sales tax collected upon the sale of goods or the provision of taxable services. Record the sales value in the Sales account, and the collected tax in the Sales Payable account.
Example
If an entity sells a product for 10,000 (pre-tax) and the sales tax is 1,500, the total amount due from the customer is 11,500.
Sales Tax Payment Journal Entry
This entry is used to record the payment of the net sales tax due to the tax authority. It reduces the liability recorded in the "sales tax Payable" account and credits the corresponding amount to the bank or cash account.
Example
If the net Sales tax payable amounts to 600 and the entity settles this amount from its bank account, the journal entry would be as follows:
Value Added Tax (VAT) Journal Entries
Accounting entries for Value Added Tax (VAT) record transactions related to VAT on sales and purchases, recognize amounts collected from customers as a tax liability, and settle this liability at the end of the tax period by offsetting output tax against deductible input tax.
Specifically, when the entity sells a good or provides a VAT-subject service, it records the sale value in the Sales account. The VAT collected from the customer is recorded separately in the VAT Payable account, as it represents an amount the entity collects on behalf of the customer and must remit to the tax authority under applicable laws and regulations.
Explore more on this topic: How to Calculate VAT in Saudi Arabia: Formula & Examples
The key accounting entries related to VAT are as follows:
VAT on sales Journal Entry:
This entry is used when a VAT-subject sale occurs; the sales value is recorded in the Sales account, and the tax collected from the customer is recorded in the VAT Payable account, recognizing the entity's liability.
Example
Let us assume a company sold goods worth 10,000 Riyals, and the Value Added Tax (VAT) due was 1,500 SAR.
Consequently, the tax invoice shows the value of the supply and the tax due separately, or indicates that the consideration includes tax, in accordance with tax invoicing requirements.
VAT Payment Journal Entry
This entry is used to pay the net VAT due to the tax authority after filing the tax return; it reduces the liability recorded in the "VAT Payable" account and records the payment amount on the bank account's credit side.
Example
Let us assume that the net VAT payable by an entity for the tax period amounts to 3,000 SAR, and the entity subsequently pays this amount to the tax authority from its bank account; the accounting entry is recorded as follows:
Below, we outline the importance of journal entries, noting that they are not merely a process of recording debits and credits, but rather serve as the foundation for the VAT reconciliation process.
Based on the Daftra team's experience with a private retail company in Riyadh, the company's accountant encountered a challenge while preparing the VAT reconciliation for a specific tax period.
Taxable sales amounted to 200,000 SAR (pre-VAT), while taxable purchases totaled 120,000 SAR (pre-tax).
Upon reviewing the accounting entries and preparing the tax reconciliation, the following figures were identified:
- Output VAT: 30,000 SAR
- Deductible input VAT: 18,000 SAR
- Net VAT payable: 12,000 SAR
The challenge for the accountant lay not merely in calculating the tax, but in ensuring sales and purchase invoices were linked to the correct accounting accounts before preparing the tax return. Once the entries were reviewed and the output and input taxes were correctly classified, the accountant could accurately determine the net tax payable.
Use our free online VAT Calculator in the KSA to calculate VAT easily.
How Does Daftra Help You Generate Tax Journal Entries?
Daftra accounting software automatically generates accounting entries when you record invoices and financial transactions, displays tax amounts, and routes them to the designated tax accounts.
Additionally, Daftra lets you manually create tax entries and include tax components within the journal entry itself, ensuring accurate reporting. You can also perform tax account reconciliations using journal entries at the end of the period.
Frequently Asked Questions
What are the Value Added Tax rates in Saudi Arabia?
The standard VAT rate in Saudi Arabia is 15%, with certain supplies subject to a zero rate or exemption.
What are tax provision entries?
These are the accounting entries used to record income tax expense and the associated tax liability for the accounting period before actual payment; unpaid current tax is recognized as a liability, while overpayments are classified as an asset.
What are withholding and additional tax rates?
Withholding tax rates in Saudi Arabia vary by payment type and beneficiary; no single rate applies to all transactions.
Applicable rates include 5% and 15%, depending on the type of income and the terms of the transaction.
What are some examples of adjusting entries?
Adjusting entries include recognizing unpaid accrued expenses, uncollected accrued revenues, prepaid expenses that have been partially consumed, and unearned revenues that have been partially earned during the period.
They aim to allocate revenues and expenses to the specific financial period to which they relate.
What is the commercial and industrial profits tax entry?
It is the journal entry used to record the income tax expense and the tax liability due for the period; the tax is not determined by applying a fixed rate to each individual item but is instead calculated based on taxable income and the regulations applicable to the taxpayer.
What is a VAT accrual entry?
It is the accounting entry used to record Value Added Tax (VAT) associated with a taxable transaction upon its occurrence, such as recording output tax on sales or deductible input tax on purchases.
What is a VAT payment entry?
This is the journal entry used to settle the net Value Added Tax (VAT) payable to the tax authority; typically, the VAT Payable account is debited, and the Bank account is credited.
| Accounts | Debit | Credit |
| VAT Payable | xxx | - |
| Bank | - | xxx |
How do you record an income tax expense?
Income tax expense is recorded when the income tax liability for the period is recognized, and the journal entry is:
| Accounts | Debit | Credit |
| Income Tax Expense | xxx | - |
| Income Tax Payable | - | xxx |
Upon payment of the tax, the journal entry becomes:
| Accounts | Debit | Credit |
| Income Tax Payable | xxx | - |
| Bank | - | xxx |
Conclusion
In conclusion to this article, we recognize the importance of tax accounting treatments and journal entries in maintaining the integrity of financial software and ensuring compliance with applicable tax legislation. By accurately estimating and recording taxes, companies and individuals can avoid financial penalties and maintain financial stability.
Tax management requires a precise understanding of tax software and local and international laws, along with advanced accounting techniques and best practices for recording and estimation. By employing these tools, organizations can achieve tax compliance and improve financial management.
Finally, companies and individuals must understand the importance of tax accounting treatments and journal entries, and improve internal tax processes and software to ensure full compliance and achieve financial stability and business success.


 Invoicing
 POS
 Offers
 Installments
 Sales Commission
 KSA E-Invoice Software
 EGY E-Invoice Software
 JO E-Invoice Software
 E-Invoice Software
 Chart of Accounts
 Asset Management
 Cost Centers
 Expenses
 Cheque Cycle
 UAE VAT-Tax
 Product Management
 Purchases
 Purchase Cycle
 Suppliers
 Requisitions
 Stocktaking
 Organizational Structure
 Personnel Management
 Attendance and Leave
 Contracts
 Payroll
 Requests
 Work Orders
 Booking Management
 Rental and Unit Management
 Time Tracking
 Work Flow
 Lease Contracts
 Manufacturing Management
 Client Follow-Up
 Loyalty Points
 Points and Credits
 Memberships
 Insurance Management
 Daftra ERP Full App
 Point of Sales App
 Point of Sales for Desktop – Support Offline Mode
 AI Expenses Scanner App
 Employee Attendance, Sign & ESS App
 E-invoice Reader App
 Inventory Stocktaking App